Markets Tighten in U.S. Life Science Sector
Winter 2012
This significant level of investment is having a mixed impact on the market for life science and biotech space, especially in the research and development sector. Though market activity is picking up in most life science clusters throughout the United States, speculative construction of R&D facilities continues to be rare in nearly all clusters, demonstrating market awareness of constricted demand, according to Jones Lang LaSalle.
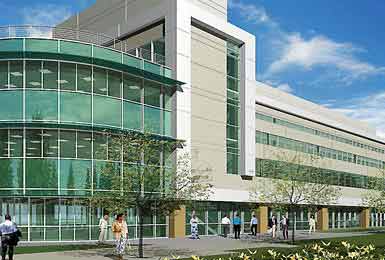
One well established life science cluster where spec construction activity is taking place is in the neighboring San Francisco Bay eastern shore communities of Emeryville and Berkeley. In Emeryville, life science developer Wareham Development is currently putting the finishing touches on its 99,000-square-foot Greenway project, a $65 million LEED Gold pre-certified R&D lab development. The project is the first spec lab facility to be built in the area since Wareham completed the 245,000-square-foot EmeryStation East in 2007.
The life science real estate market on the eastern shore has close to a zero percent vacancy, and throughout the San Francisco Bay area, the availability of space is tight. This is partly due to demand and partly to the fact that several large-scale properties previously used by biotech firms have been taken over by technology companies such as Salesforce, VMWare, and Google.
Nevertheless, demand for life science lab facilities in the East Bay is solid. Ongoing work into a variety of life science-related technologies, such as stem cell research and the development of more efficient biofuels coming out of the nearby University of California at Berkeley, is prompting much of this demand. Another potential impetus for life science industry expansion in the immediate area is Lawrence Berkeley National Laboratories' search for a second campus within 20 to 25 minutes of its existing facility in the Berkeley Hills.
While areas such as the San Francisco Bay, Boston, and Seattle continue to top the U.S. list as established markets for life science industry expansion, Los Angeles and the Washington, D.C., region are now also considered established clusters. Los Angeles' vast number of hospitals, universities, and research facilities and its large college-educated population should help propel its growing biotechnology sector to complement its mature medical device presence. Washington, D.C./suburban Maryland's close ties with government agencies and world-renowned academic research centers have supported a wave of early start-ups that have given way to mid-stage companies ripe for acquisition by major pharmaceutical companies. Rounding out the top-seven established clusters are Philadelphia and San Diego. Other U.S. cities emerging as key players in this sector include Minneapolis, Chicago, Denver, Houston, Florida, Atlanta, and Indianapolis.
Recent Project Announcements
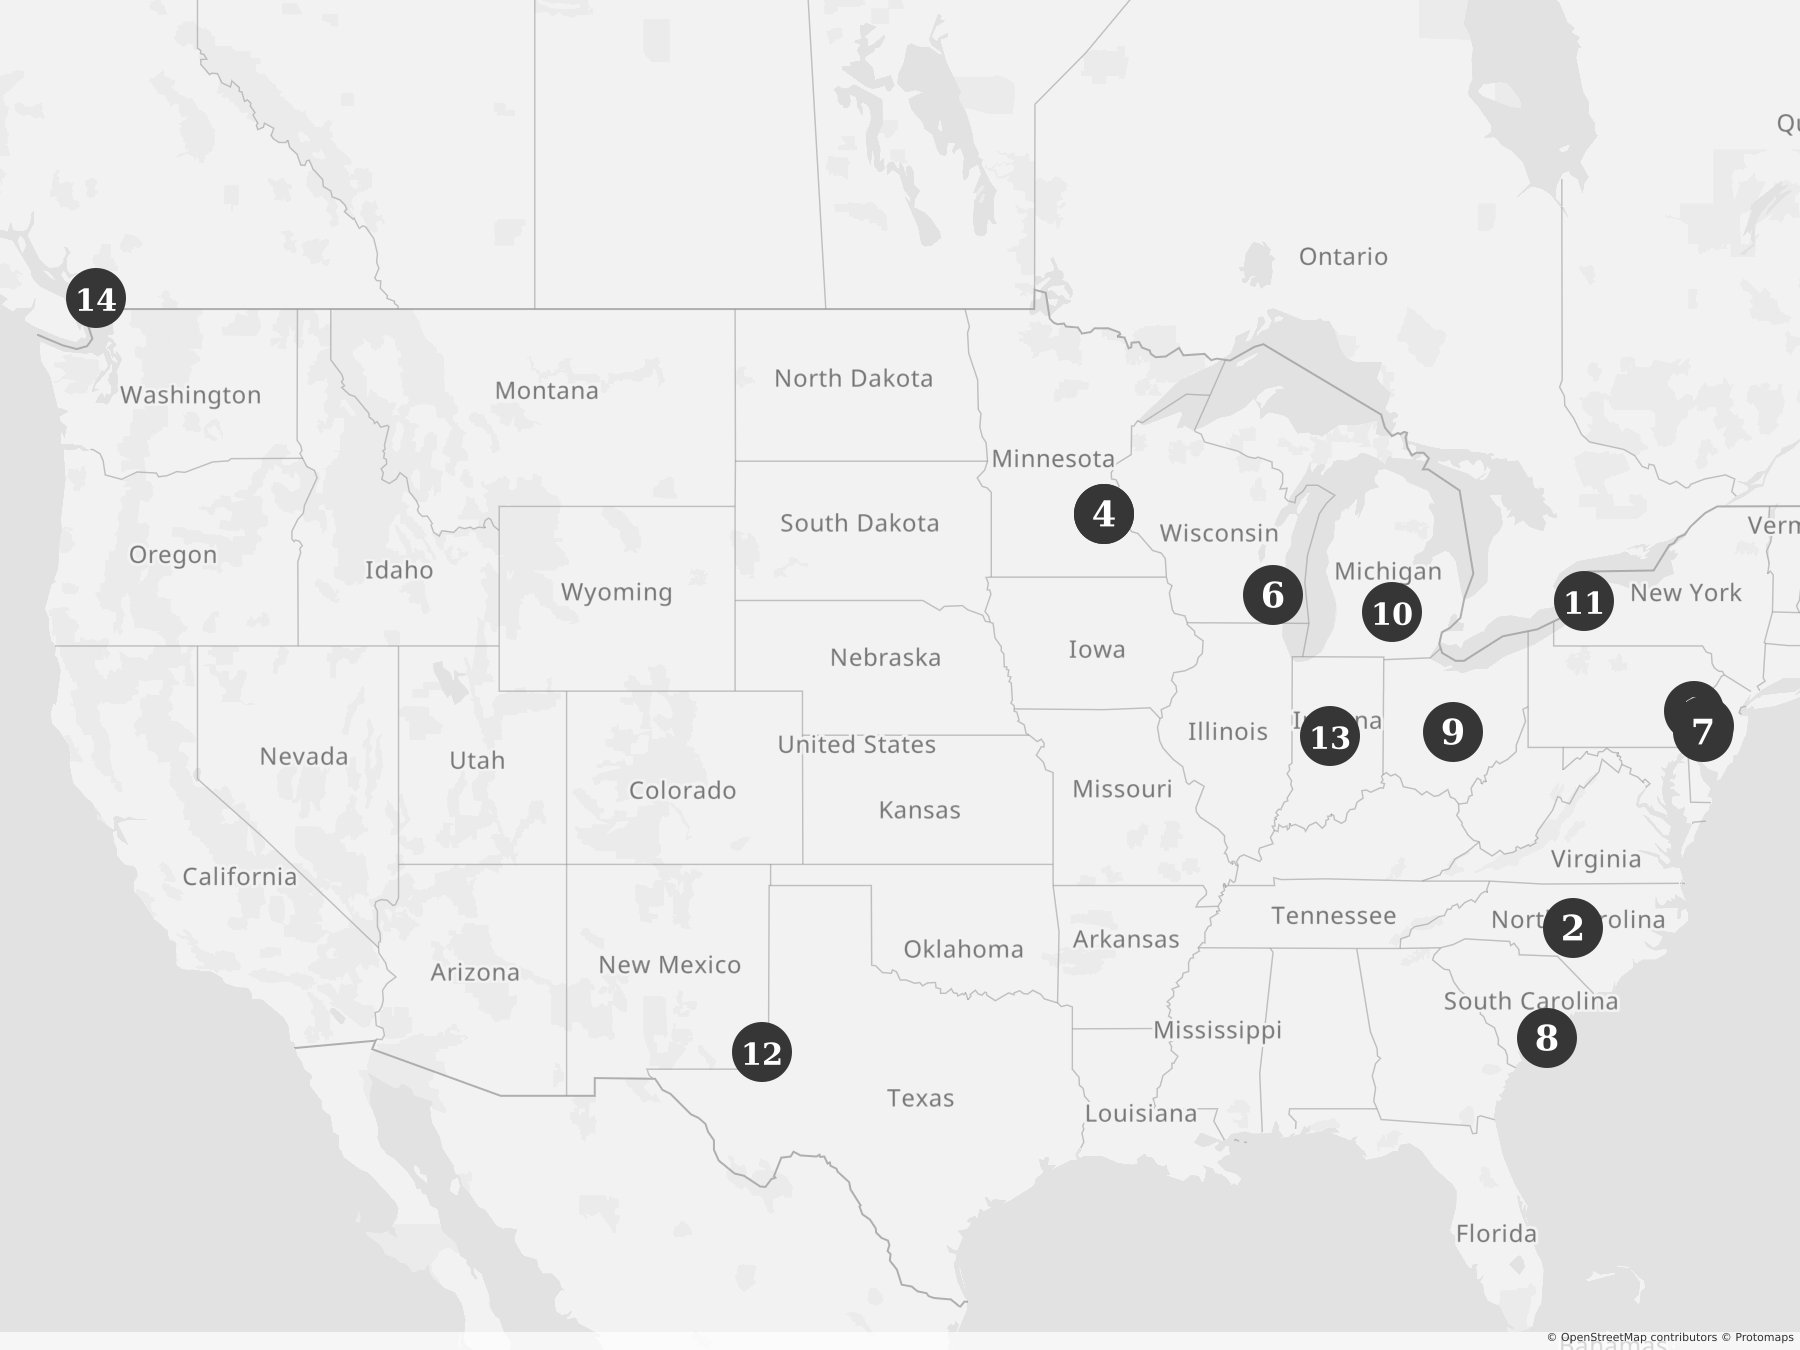
Glenmark Pharmaceuticals Plans Allentown, Pennsylvania, Distribution Operations
10/31/2026
Italy-Based Bracco Plans Sanford, North Carolina, Manufacturing Operations
10/30/2026
Ecolab Expands Eagan, Minnesota, R&D Operations
10/27/2026
Ecolab Expands Eagan, Minnesota, Operations
10/27/2026
Merck Expands Montgomery County, Pennsylvania, R&D-Manufacturing Operations
10/21/2026
Aleris Nutrition Plans Menomonee Falls, Wisconsin, Production Operations
10/19/2026
GSK Expands Montgomery County, Pennsylvania, Manufacturing Operations
10/16/2026
Obatala Sciences Establishes Charleston County, South Carolina, Operations
10/12/2026
Bayer Plans New Albany, Ohio, Pharmaceutical Manufacturing Operations
10/03/2026
Niowave Expands Lansing, Michigan, Production Operations
09/30/2026
Italy-Based IMA Life North America Expands Tonawanda, New York, Pharmaceutical Operations
09/29/2026
Eden Radioisotopes Plans Lea County, New Mexico, Production Operations
09/26/2026
RayzeBio Plans Whitestown, Indiana Radiopharmaceutical Manufacturing Operations
09/02/2026
Germany-Based Evonik Plans Vancouver, British Columbia, Manufacturing Operations
08/30/2026
Most Read
-
Top States for Doing Business in 2026: Where Competitive Advantage Becomes Project Certainty
Q3 2026
-
Why Great Sites Get Eliminated: The Critical Role of Information Presentation in Site Selection
Q3 2026
-
2025’s Top States for Business: How the Winners Are Outpacing the Rest
Q3 2025
-
Economic Developer Role Shifting from Deal-Making to Systems Stewardship
Q1 2026
-
New Markets Tax Credits Are Now a Permanent Part of the Deal Stack
Q3 2026
-
Industrial Location Decisions Follow the Freight
Q3 2026
-
Space and Defense Are Becoming One Industrial Ecosystem
Q3 2026