Industrial Manufacturers’ Optimism Reflected in Expectations of Higher Revenue Growth, Increased Capital Spending
Q1 2017
More than three quarters (78 percent) of those surveyed by PwC believe the domestic economy is growing — up from only 38 percent in Q2/2016 and edging closer to the levels of optimism reached back in 2006 before the Great Recession, when 92 percent of the surveyed companies were optimistic about U.S. economic growth. When it comes to near-term economic prospects (over next 12 months), 57 percent said they are optimistic.
However, these same industrial manufacturing panelists aren’t as optimistic about the outlook for the world economy — only 30 percent expressed optimism about the global economy over the next 12 months; 54 percent remained uncertain; while 16 percent were pessimistic. These lingering doubts reflect a persistent dichotomy between industrial manufacturers’ perceptions of the health of the U.S. and worldwide economies.
In line with their optimism about the U.S. economy, 85 percent of industrial manufacturers said they expect positive revenue growth in 2017, predicting their own companies’ average revenue growth would increase by 4.6 percent from 3.6 percent a year ago. And despite their pessimism about the global economy, they still expect international sales to represent a third of their total revenues.
With increased revenue comes industrial manufacturers’ plan to increase capital spending over the next 12 months, rising to the 60 percent level and nearing the high of 67 percent in the fourth quarter of 2011. Also, plans for new hiring remained fairly stable at 35 percent, compared to 32 percent two quarters ago.
The top opportunities industrial manufacturers will pursue in 2017 to achieve their corporate objectives include improved customer experience (cited by 63 percent of those surveyed), greater cost containment (57 percent), technology advances (55 percent), product and service innovation (53 percent), increased worker productivity (45 percent), and market expansion for new products/services (43 percent).
The challenges to growth over the next 12 months cited by the industrial manufacturers surveyed include monetary exchange rate barriers (48 percent), lack of demand (43 percent), and legislative/regulatory pressures (43 percent).
Recent Project Announcements
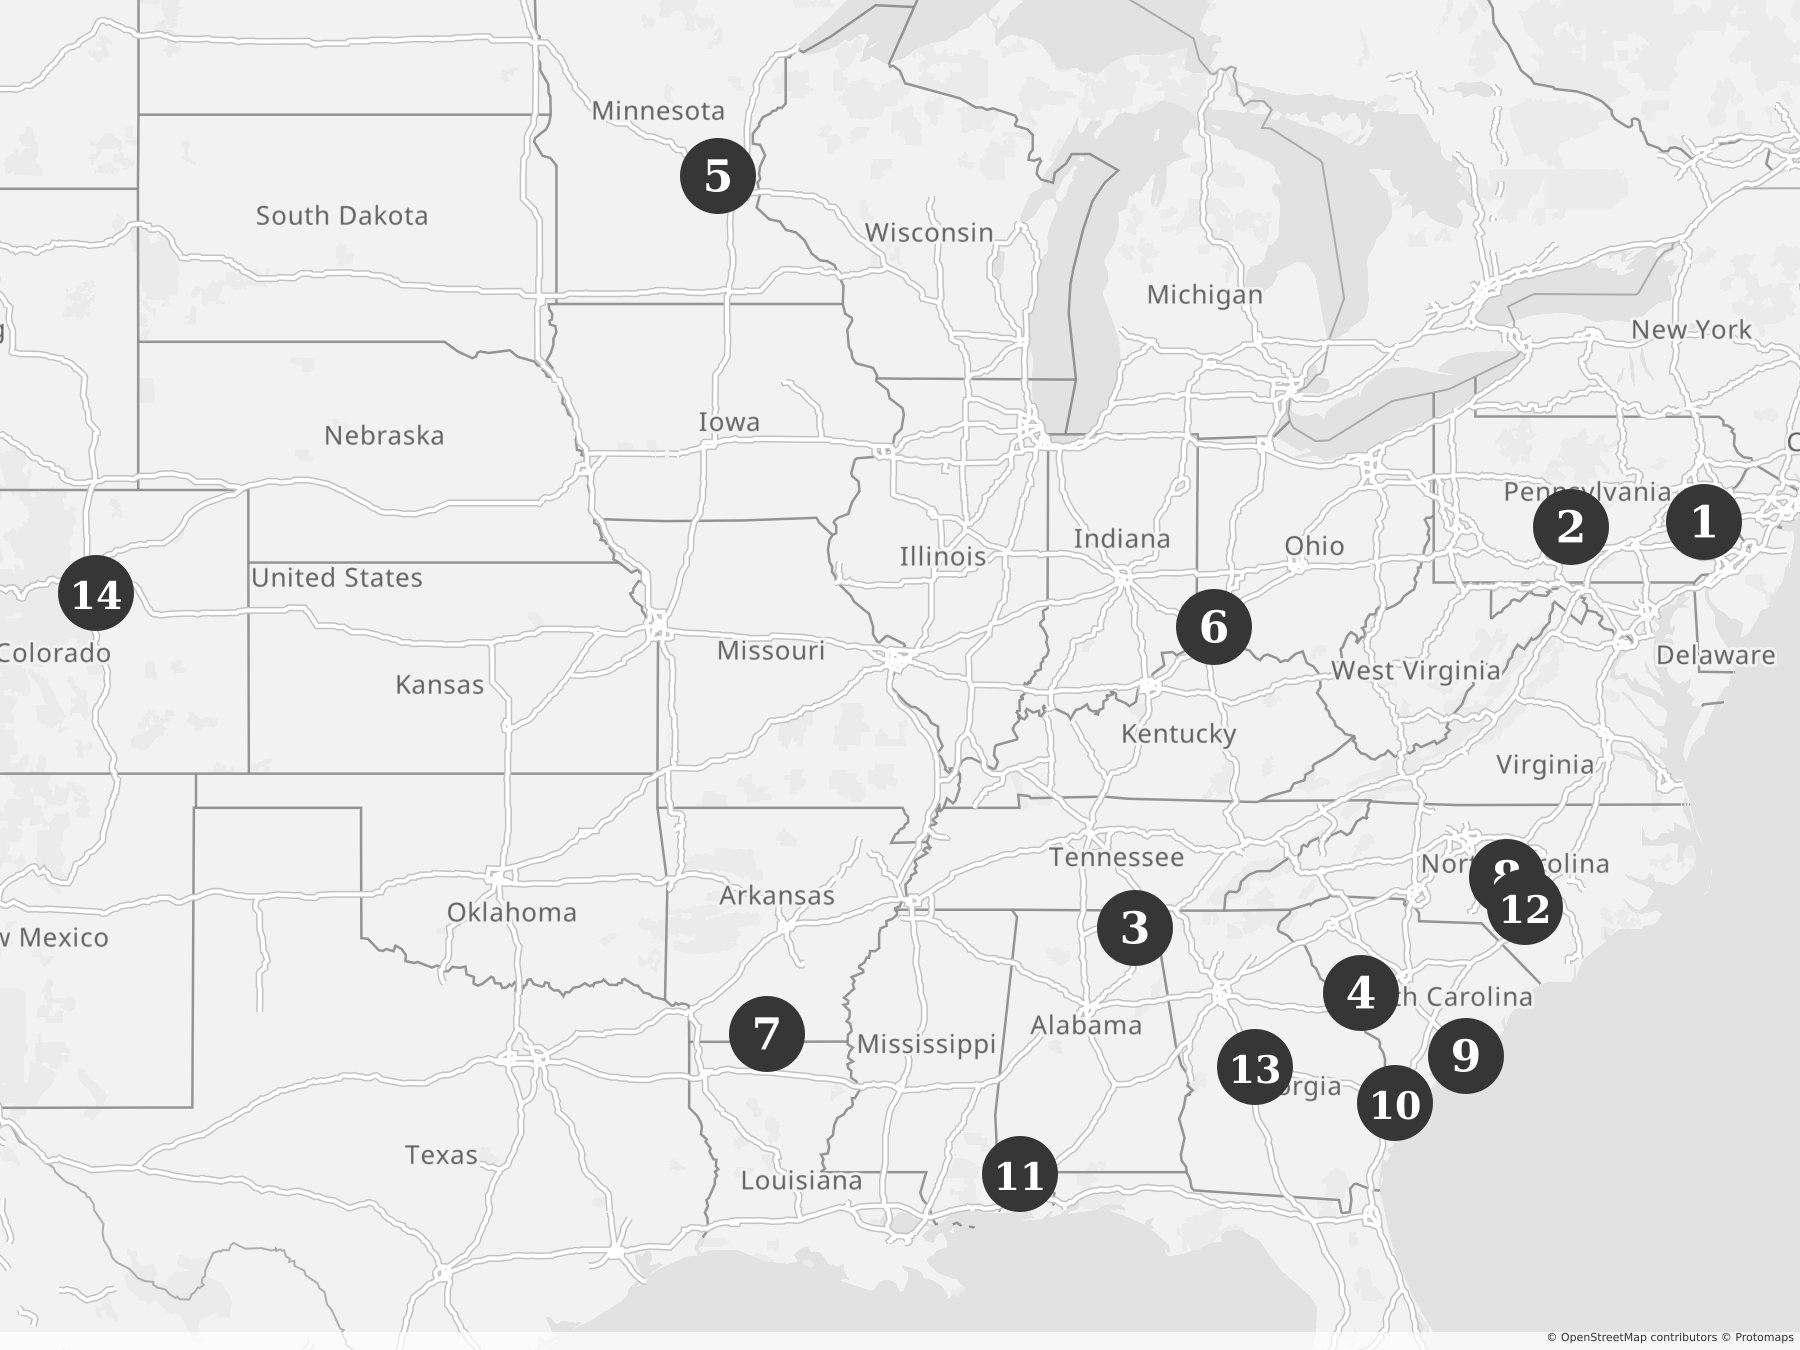
Glenmark Pharmaceuticals Plans Allentown, Pennsylvania, Distribution Operations
10/31/2026
Superior Huntingdon Composites Expands Huntingdon, Pennsylvania, Fiberglass Production Operations
10/31/2026
Helix Electric Plans Hollywood, Alabama, Manufacturing Operations
10/31/2026
Amick Farms Plans Edgefield County, South Carolina, Operations
10/31/2026
Gradian Thermal Solutions Establishes Dayton, Minnesota, Manufacturing Operations
10/30/2026
AMEND Consulting Expands Cincinnati, Ohio, Operations
10/30/2026
Canfor Southern Pine Expands El Dorado Arkansas, Operations
10/30/2026
Italy-Based Bracco Plans Sanford, North Carolina, Manufacturing Operations
10/30/2026
Nash Technologies Expands Charleston, South Carolina, Operations
10/30/2026
Mitsubishi Power Americas Expands Chatham County, Georgia, Manufacturing Operations
10/28/2026
Premium Plate Expands, Mobile County, Alabama, Operations
10/28/2026
Omega Industries Plans Fayetteville, North Carolina, Manufacturing Operations
10/27/2026
Germany-Based Audi Plans Peach County, Georgia, Manufacturing Operations
10/27/2026
Boom Supersonic Expands Centennial, Colorado, Manufacturing Operations
10/27/2026
Most Read
-
Top States for Doing Business in 2026: Where Competitive Advantage Becomes Project Certainty
Q3 2026
-
Why Great Sites Get Eliminated: The Critical Role of Information Presentation in Site Selection
Q3 2026
-
2025’s Top States for Business: How the Winners Are Outpacing the Rest
Q3 2025
-
Industrial Location Decisions Follow the Freight
Q3 2026
-
Space and Defense Are Becoming One Industrial Ecosystem
Q3 2026
-
Economic Developer Role Shifting from Deal-Making to Systems Stewardship
Q1 2026
-
New Markets Tax Credits Are Now a Permanent Part of the Deal Stack
Q3 2026