Assessing Emerging Markets for Cross-Border Location Strategies
Conducting an accurate financial assessment of emerging markets for global manufacturing means the difference between project success and failure.
Winter 2011
Assemble the Right Project Team
The only way to obtain an accurate view of an investment is to carefully coordinate project specifications, assumptions, and financial model architecture. For all three to work smoothly, input from a team of functional subject matter experts is needed. This project team should include representatives from company strategy, finance, tax, HR, supply chain, real estate, purchasing, sales and marketing, and engineering departments.
This team ensures that model logic for all inputs (project assumptions and specifications) that will drive the financial analysis is sound. It is not uncommon for the modeling exercise to require multiple rounds of refining until the team is satisfied with the harmony of the inputs. During this planning stage, the model philosophy and costs that the model should reflect as part of company responsibility, versus external to the model and the customer's responsibility, are paramount. This consideration will affect how to model revenue, logistics costs, and tax.
Five Categories of Financial Assumptions
The major assumptions supporting the financial assessment can be divided into five categories:
Revenue - volume of products sold or payments received from customers for company products;
Cost of Goods Sold (COGS) - the costs of developing, manufacturing, storing, and distributing products;
Operating expenses - general costs not directly associated with the production of products;
Direct tax - the amount of taxes a company pays to federal, state, and local governments based on its level of income; and
Other factors - other considerations that influence a project.
1. Revenue
Projected revenue assumptions of a new operation are critical to financial performance. Developing revenue assumptions is a challenging task, particularly for new investments into regions in which a company has limited presence or sales experience. The assumptions require a forecast from the strategy or corporate development organization and input from sales and marketing considering product mix, selling price, destination, and unit price increases for inflation or other pricing strategies.
Because an investment's financial feasibility is closely tied to revenue, the implications of inaccurate revenue assumptions can significantly impact ultimate output and the metrics of financial performance. To avoid overstating the financial performance of an investment and inflated stakeholder expectations, revenue should be modeled under best- and worst-case scenarios. Testing revenue assumptions using both potential customers and suppliers may be necessary.
2. Cost of Goods Sold (COGS)
COGS inputs are the first of two categories of pre-tax costs. COGS inputs model the direct costs attributed to the production of goods sold by a company, such as raw materials, transportation, direct labor, and utilities. COGS data inputs can greatly vary geographically. A key consideration when modeling raw materials is the supply source and whether the company will continue to leverage its existing supply base or move to a higher percentage of in-region or in-country supply.
Transportation costs also vary greatly. Third-party logistics (3PL) provider rate quotes can range based on in-region and in-country capabilities of the 3PL, and will vary for each shipment segment. Labor practices and regulation vary significantly among countries, and developing inputs to accurately reflect shift premiums, overtime, collective bargaining agreements, and benefit loads takes time. Even obtaining utility costs can be challenging due to temporal cost variability based on consumption time or the variability in water charges based on industrial park capabilities, water capacity, and extraction rights. 3. Operating Expenses
Operating expense inputs consist of costs for start-up expenses, indirect labor, indirect tax, depreciation, and other selling, general, and administrative costs. Operating expense costs are generally lower than COGS cost inputs, except for depreciation. Like COGS inputs, most operating expense inputs are geographically variable, and the method of calculation can change radically locally and nationally. Sales tax (or value added tax) and its treatment in the model presents another key concern. When modeling, it is necessary to determine if the company will show the tax impact, often in excess of 15 percent, in its financial view of the project (effectively reducing the margin on revenue) or whether the customer will incur the tax.
4. Direct Tax
Typically, the formula for calculating taxable income is taxable earnings less loss carried forward, multiplied by the applicable income tax rate (standard or preferential). Since many countries utilize income tax as an incentive, income tax liability can vary significantly between countries. This is a critical consideration for industries with products that have high gross margins, which translates to more taxable income. Income tax rates in many countries often exceed 25 percent, but some countries offer three-, five-, 10-, and possibly 20-year exemptions or reductions from income tax.
5. Other Factors
In addition to revenue, COGS, operating expenses, and direct tax, external market factors influence longer-term financial merits of direct investment, such as inflation, currency exchange rates, and incentives. Inflation directly affects operating costs and will increase the cost denominator driving most financial calculations over the analysis period.
Currency exchange policy falls within exchange rates tied to the U.S. dollar and highly volatile free market rates. Businesses can hedge exchange rates, although they are difficult to predict.
Companies cannot control incentives policies as easily, however, which can notably affect project economics. Federal, state, and local governments can often extend incentives to attract direct investment, thereby making a location more financially desirable. Programs that reduce one-time costs (connection fees, import duty exemptions, infrastructure subsidies, land prices, recruiting and training) and recurring costs (utility rate tariffs, tax reductions) are all common.
Measuring Output and Performance
The model would ideally include output for key metrics to lend insight into the investment decision, including free cash flow (FCF), cumulative net present value (NPV), and return on invested capital (ROIC). Free cash flow is a measure of financial performance that provides visibility and allows a company to know exactly when a project generates a positive return. Cumulative NPV enables an understanding of how much the project will add - or detract - to the enterprise. Return on invested capital is the percent amount earned on the total invested capital, or how effectively the company has used the invested money. A model will often include other key, company-specific performance metrics such as cost per unit of output.
Modeling emerging markets is complex and requires significant time and resources to achieve accuracy. If the activity is not well coordinated and model inputs are poorly calibrated, there is a higher risk for misleading results. Ensuring accuracy begins with developing a tight set of project specifications and assumptions. The model architecture must then be able to capture a wide range of highly variable and interrelated data inputs. If a company fails to develop a comprehensive view of the investment, it will be impossible to develop appropriate outputs to measure the investment's merits.
-
Matt Jackson, Executive Managing Director , JLL
Matt Jackson is an Executive Managing Director in JLL's Business Consulting Group. With more than 30 years of experience, Mr. Jackson is responsible for assisting companies with global strategy, location footprint configuration, location/site selection, portfolio and occupancy strategy, and global incentives negotiations. He is originally from New Zealand and based in Washington, D.C.
-
Matt Highfield, Senior Vice President, Strategic Consulting, Jones Lang LaSalle
Matt Highfield brings more than 12 years of management consulting experience advising large corporate clients on global location strategy and platform optimization. Previously a Managing Principal with Cushman & Wakefield’s Global Business Consulting Practice, Highfield focused on the development of competitively sustainable global business platforms and the selection of locations synergistic with corporate cost and quality goals. In doing so he conducted detailed field evaluations of complex emerging markets, developed redeployment strategies and business case scenarios, performed inspections and qualifications of sites and facilities, and negotiated real estate and economic development incentives. He received a bachelor’s degree from Macalester College in St. Paul, Minn and a master’s degree from University of North Carolina at Charlotte.
Recent Project Announcements
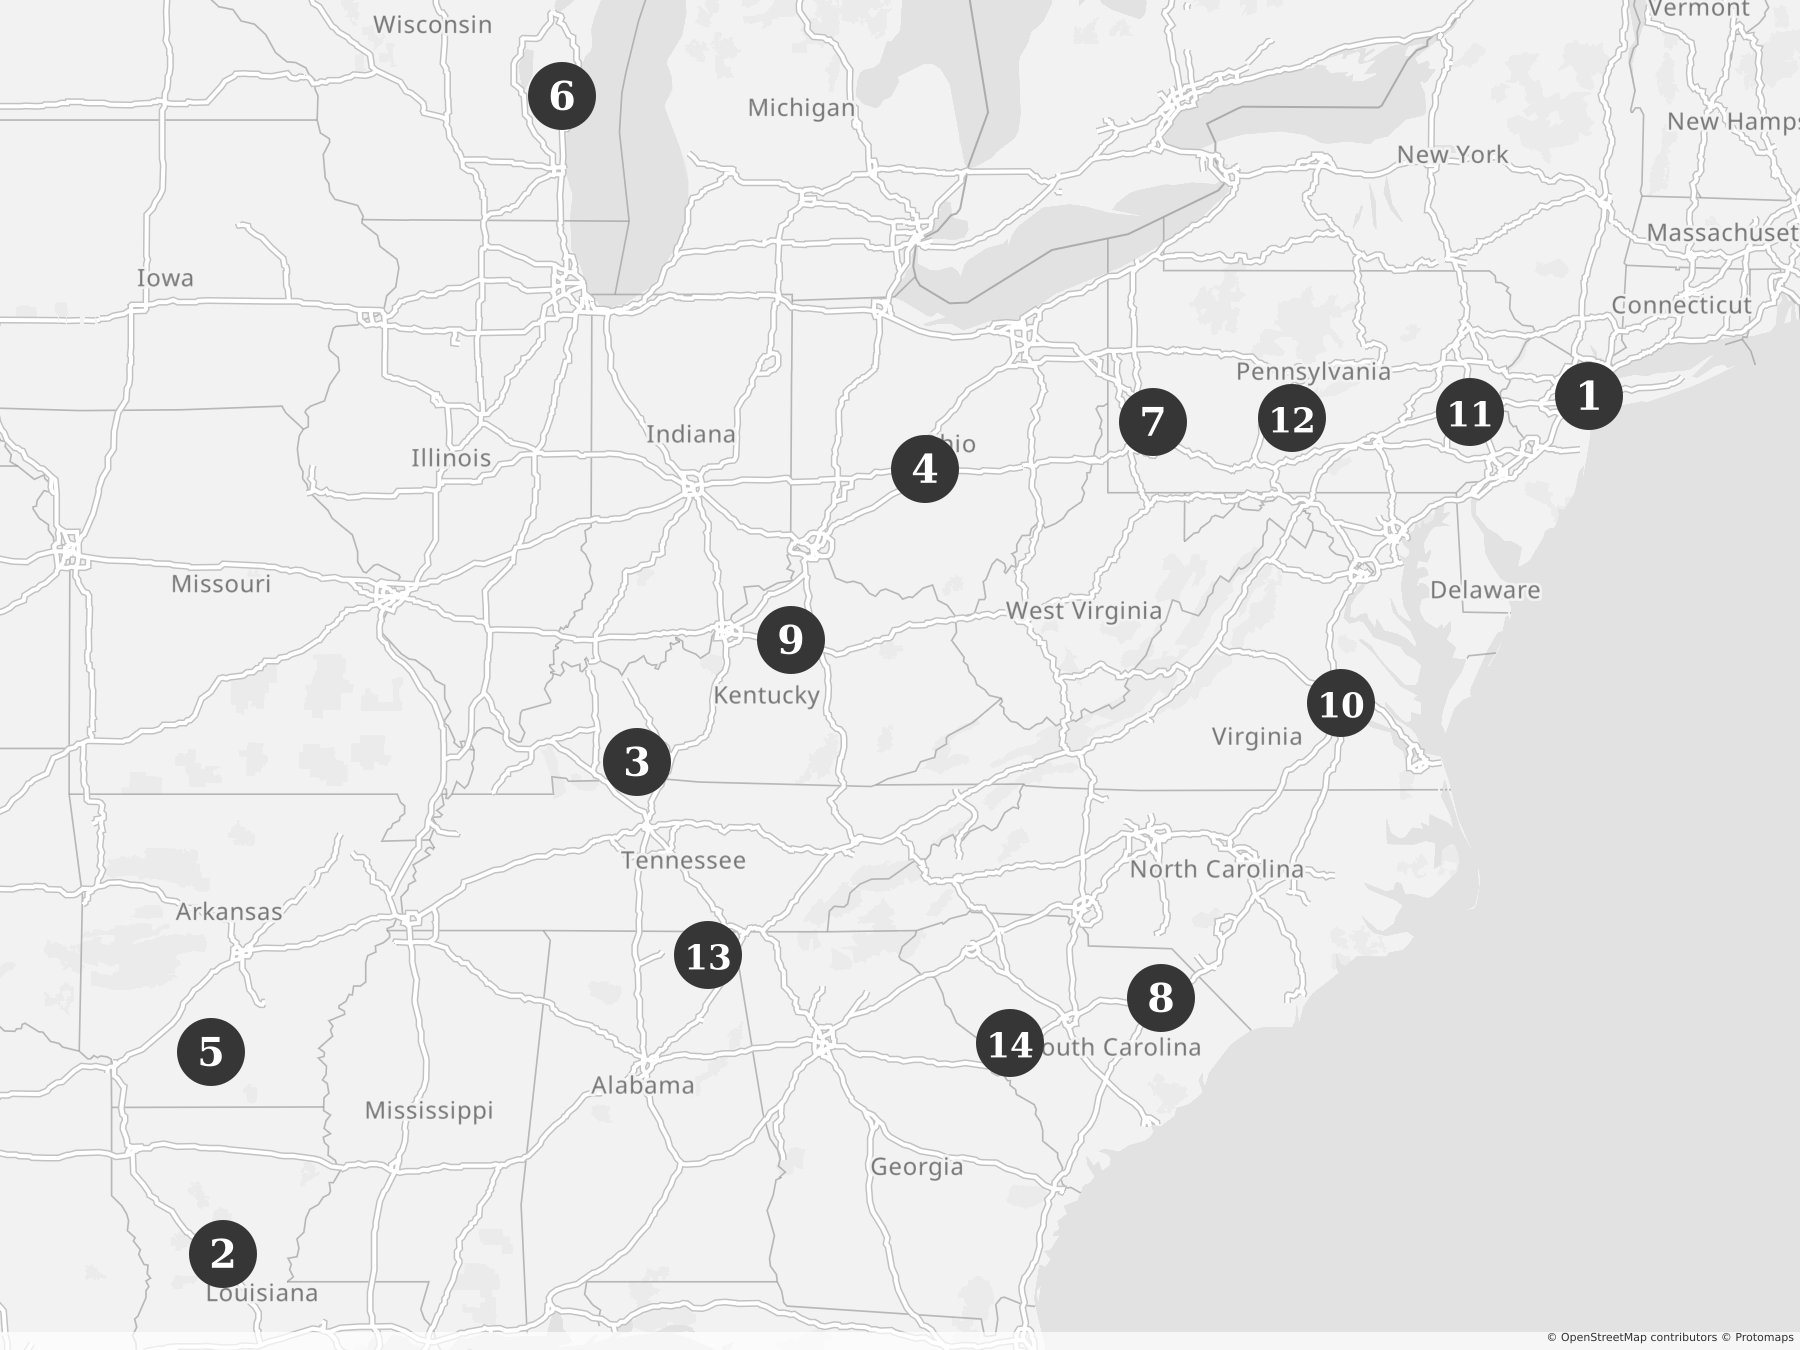
Grow Therapy Expands New York City Operations
11/05/2026
Robinson Carbon Plans Alenandria, Louisiana, Biochar Operations
11/05/2026
ClearFlow Metalworks Plans Logan County, Kentucky, Aluminum Manufacturing Operations
11/03/2026
Forgent Power Solutions Plans Columbus, Ohio, Operations
11/03/2026
Lockheed Martin Expands Camden, Arkansas, Production Operations
11/03/2026
Sartori Company Expands Plymouth, Wisconsin, Production Operations
11/02/2026
Tronix3D Expands Pittsburgh, Pennsylvania, Manufacturing Operations
11/02/2026
South Korea-Based Hwasung Group Plans Florence, South Carolina, Manufacturing Operations
11/02/2026
Japan-Based Nissin International Transport Plans Franklin County, Kentucky, Distribution Operations
11/01/2026
Dominion Packaging Expands Henrico, Virginia, Operations
11/01/2026
Glenmark Pharmaceuticals Plans Allentown, Pennsylvania, Distribution Operations
10/31/2026
Superior Huntingdon Composites Expands Huntingdon, Pennsylvania, Fiberglass Production Operations
10/31/2026
Helix Electric Plans Hollywood, Alabama, Manufacturing Operations
10/31/2026
Amick Farms Plans Edgefield County, South Carolina, Operations
10/31/2026
Most Read
-
Top States for Doing Business in 2026: Where Competitive Advantage Becomes Project Certainty
Q3 2026
-
Why Great Sites Get Eliminated: The Critical Role of Information Presentation in Site Selection
Q3 2026
-
2025’s Top States for Business: How the Winners Are Outpacing the Rest
Q3 2025
-
Space and Defense Are Becoming One Industrial Ecosystem
Q3 2026
-
Economic Developer Role Shifting from Deal-Making to Systems Stewardship
Q1 2026
-
New Markets Tax Credits Are Now a Permanent Part of the Deal Stack
Q3 2026
-
Industrial Location Decisions Follow the Freight
Q3 2026