Industry Sea Changes Affecting U.S. Shipping Gateways
Damage from recent hurricanes could have a ripple effect across U.S. seaports, underscoring the rising demand for more sophisticated industrial real estate and infrastructure.
Q4 2017
Demand for industrial real estate across the U.S. is stronger than ever, with no small thanks owed to the newly expanded Panama Canal. It’s been just over a year since the major maritime corridor completed its $5 billion expansion project, but its effects are already clear, particularly around East and Gulf Coast ports. The market was more than ready for a new, more efficient way to connect people to goods.
Larger ships and greater volumes are making sophisticated shelf space a hot commodity in all 14 of the port markets tracked in JLL’s 2017 Seaport Outlook, and developers are doing their part to answer the call for more modern warehouse and logistics space. More than 25 million square feet of industrial real estate is being built in top U.S. ports as we speak, with most (65 percent) of that construction centered around the East and Gulf coasts.
Five Trends Influencing Seaport Real Estate Strategy
1. East and Gulf Coast ports are making waves.
The expanded Panama Canal, increased trade with Asia, and importers’ pursuit of a four-corner strategy throughout the coasts are creating major momentum along the eastern and southern coasts. Recently, mid-Atlantic and southeastern seaports have experienced a 20 percent uptick in trade volumes compared to just 5 percent growth on the West Coast. All this cargo means good space is getting harder to find. For example, over the last two years alone, East Coast ports including New York/New Jersey and Jacksonville have seen the biggest drop in vacancy rates.
The expanded Panama Canal, increased trade with Asia, and importers’ pursuit of a four-corner strategy throughout the coasts are creating major momentum along the eastern and southern coasts. 2. M&A is changing the players and the map, adding uncertainty.
The four long-standing shipping alliances have become a trio, with now just three alliances masterminding 90 percent of the world’s trade routes. This shift could disrupt control and travel routes in unseen ways. And as carriers work out new ways to stay competitive and reduce costs, industrial real estate tenants may find they need to become more agile in keeping up with industry change.
3. Larger ships plus fewer port calls? Expect more competition.
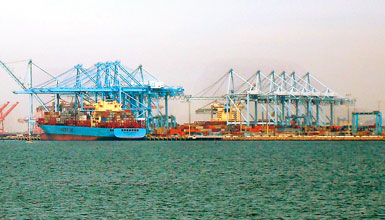
More ocean carriers are bringing larger vessels, across all cargo types, to U.S. ports now that the Panama Canal has expanded. Meanwhile, port leaders have also been expanding their own capacity, deploying new cranes, dredging channels, deepening berths, and removing air draft restrictions for some time. With more ports now able to accommodate their massive cargo loads, shipping liners could decide to cut the number of port calls they make, which will only intensify fierce regional port competition.
4. First mile strategy is spurring technology advances — but there’s a catch.
Efficient e-commerce is utterly dependent on efficient trucking, and the trucking industry is responding by ramping up technology strategy, such as incorporating autonomous vehicles into their fleets. But technology can’t eliminate congestion on the roads, especially in and around crowded ports. A complex, multi-year infrastructure overhaul is necessary to address these growing snarls, but that would mean slowing down delivery times and driving up operating costs in the meantime.
5. The rail industry is becoming a viable alternative to trucking.
Many shippers have been finding rail is a less expensive and more sustainable option than trucking, with intermodal loads now accounting for more than half of railcar volumes — 10 percent more than it was 10 years ago. And now with road congestion issues on the rise, rail is poised to become even more attractive, as long as it continues to become more nimble.
Leaders at each gateway, and all the stops in between, will experience these industry trends in different ways. But, much like weathering a hurricane or other major disruption, one key way forward will be to lay out a real estate strategy that is resilient enough to sustain long-term growth, while also being nimble enough to handle imminent change.
-
Walter Kemmsies, Ph.D., Managing Director, Economist and Chief Strategist, U.S. Ports, Airports and Global Infrastructure Group, JLL
An advisor to port authorities and major transportation and manufacturing companies, Walter Kemmsies executes initiatives to underwrite, finance and evaluate commercial property investment opportunities near seaports and airports throughout North America. He is the former chief economist for Moffat & Nichol, and continues to serve as an advisor to the U.S. Dept. of Commerce Advisory Committee on Supply Chain Competitiveness and the U.S. Dept. of Transportation’s National Task Force on Transportation Infrastructure Valuation. Kemmsies is a frequent contributor to the Federal Reserve’s Survey of Professional Forecasters and American Shipper; is active in leading industry organizations; and has been a keynote speaker at major conferences.
-
Top States for Business
2020 Top States Commentary: Significant Port Access
Logistics / Infrastructure
Seaports Coping With Rising Trade Volumes, Tight Real Estate Markets
-
Logistics / Infrastructure
In Focus: Has the Moment for Infrastructure Revival Arrived?
-
Logistics / Infrastructure
Intermodal Continues to Revolutionize Logistics and Industrial Real Estate Strategies
-

Recent Project Announcements
Australia-Based Sicona Battery Technologies Plans New Orleans, Louisiana, Headquarters Operations
09/19/2026
ArtiCast Jackson Plans Madison County, Tennessee, Operations
09/19/2026
Holly Poultry Establishes Hanover, Maryland, Production Operations
09/19/2026
TurbineOne Establishes Old Town, Maine, Innovation Operations
09/18/2026
Tampa Brass & Aluminum Expands Tampa, Florida, Headquarters Operations
09/18/2026
Toyotetsu Mid America Expands Owensboro, Kentucky, Operations
09/17/2026
Mayo Clinic Laboratories Plans Southaven, Mississippi, Operations
09/16/2026
V&S Schuler Tubular Products Expands Muskogee, Oklahoma, Manufacturing Operations
09/15/2026
Germany-Based Stöbich Fire Protection Systems Expands Dorchester County, South Carolina, Manufacturing Operations
09/14/2026
Black Bayou Energy Hub Expands-Plans Lafayette-Cameron Parish, Louisiana, Natural Gas Operations
09/14/2026
General Atomics Expands Shannon, Mississippi, Manufacturing Operations
09/14/2026
AirPro Expands Rhinelander, Wisconsin, Operations
09/13/2026
Moog Expands West Valley, Utah, Production Operations
09/13/2026
KIHOMAC Expands Davis County, Utah, Operations
09/13/2026
Most Read
-
The Shifting Landscape of Location Strategy
Q2 2026
-
Power Is the New Gatekeeper in Manufacturing Site Selection
Q2 2026
-
Avoid These Red Flags, Deal Killers, and Blunders in Site Selection
Q2 2026
-
Site Readiness Is Broken: What Manufacturers Should Demand From Their Locations
Q3 2025
-
What Site Selectors Discuss After the Site Visit Ends
Q3 2026
-
21st Annual Shovel Awards: The American Industrial Economy Remade in Real Time
Q2 2026
-
Why Relationships Still Win Projects in Site Selection
Q3 2026